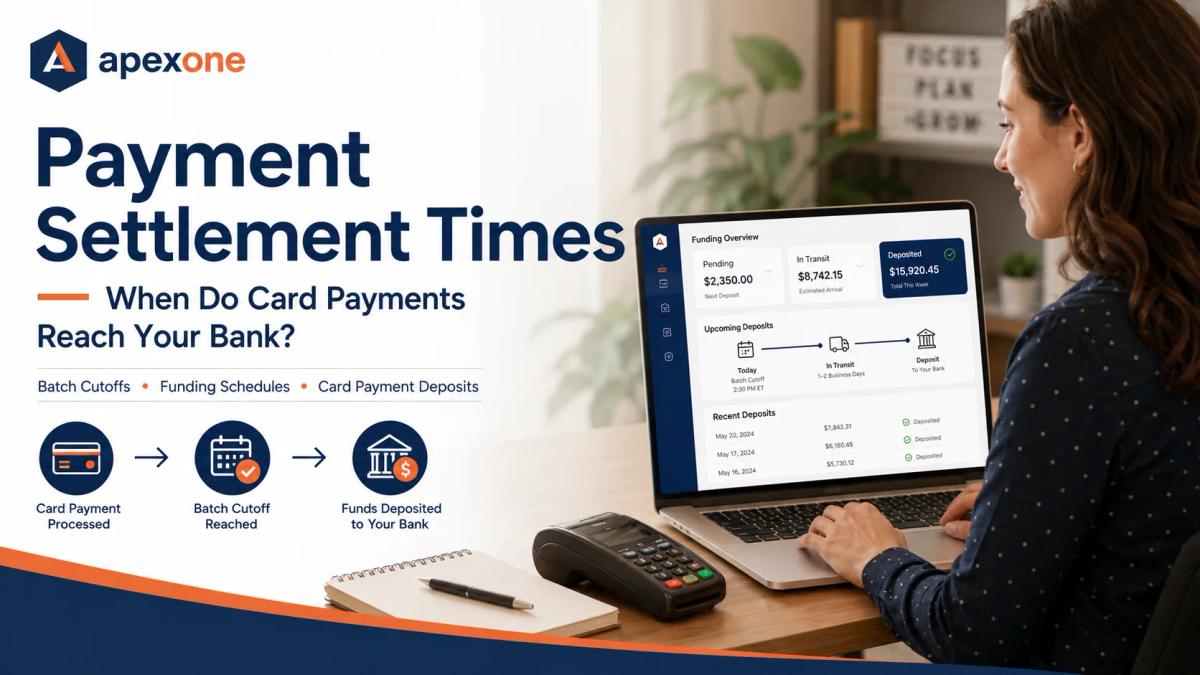
Payment Settlement Times When Do Card Payments Reach Your Bank?
Accepting a card payment and receiving the money in your bank account are not the same step. This guide explains payment settlement times, batch cutoffs, funding schedules, delayed deposits, and how small businesses can better track card payment deposits.
A customer taps their card. The payment is approved. The receipt prints. The sale is complete. For the customer, that transaction feels finished, but for the business owner, the story is not always finished yet. The bigger question is: when does that money actually reach the business bank account?
This is where payment settlement times become important. Many small business owners accept credit card and debit card payments every day, but they do not always understand what happens between the moment a payment is approved and the moment the money shows up in the bank.
That gap can create confusion. A restaurant owner may close a busy Friday night and expect the funds to appear the next morning. A retail store may process a strong weekend of sales and wonder why the deposit arrives later than expected. A healthcare office may collect patient balances but struggle to match those payments with bank deposits. A contractor may take a deposit for a job and need that money available quickly for materials.
The payment may be approved, but approval does not always mean the funds are already in the bank. A payment has to move through authorization, batching, settlement, processing, and funding before it reaches the merchant’s account. The business owner does not need to become a banking expert, but understanding the basics can help avoid stress, improve cash flow planning, and make it easier to choose the right payment processing solutions.
This guide explains payment settlement in simple business language, without making it overly technical.
What Are Payment Settlement Times?
Payment settlement time is the amount of time it takes for money from a card transaction to move through the payment system and become available to the business. In simple words, it is the time between “customer paid” and “money reached your bank.”
This timing can depend on several things, including the payment processor, merchant account setup, payment method, batch closing time, weekends, holidays, risk reviews, and the business’s funding schedule. For a small business owner, the most important point is simple: not every card payment reaches the bank immediately.
A sale can be approved today, batched later, settled after that, and funded according to the provider’s schedule. This is why payment settlement is not just a technical topic. It directly affects how business owners manage cash flow, payroll, inventory, supplier payments, and daily operations.
Authorization and Settlement Are Not the Same Thing
One of the biggest reasons business owners get confused is because they think an approved transaction means the money has already been deposited. That is not how card payments usually work.
Authorization is the first step. It means the card network and issuer have approved the transaction. The customer’s card has enough available credit or funds, and the transaction can move forward. Settlement is a later step. It is the process that moves the transaction through the payment network so the business can eventually receive the funds.
Funding or payout is when the money is actually sent to the business bank account. These steps are connected, but they are not the same.
A customer may pay at 3 PM and receive a receipt instantly, but the business may not see the money in the bank until the next business day or later, depending on the setup. For an owner managing payroll, inventory, rent, and supplier payments, this difference matters.
A payment processor should make these stages easy to understand. A business owner should not have to guess why the dashboard shows sales but the bank account shows a different number.
Why Settlement Timing Matters for Small Businesses
For a large company, a one-day delay may not feel serious. For a small business, it can matter a lot. Small businesses often run on tighter cash flow. Daily deposits may be used to buy inventory, pay staff, order supplies, handle rent, cover marketing, or manage operating expenses.
When deposits do not arrive when expected, the owner may feel like something is wrong even when the payment is simply following the normal funding schedule. A restaurant may need weekend sales to cover Monday payroll. A retail store may need card payment deposits to restock inventory. A healthcare practice may need patient payments to match billing reports. A contractor may need deposit funds before ordering materials. A salon may rely on daily card payments to manage staff commissions and product purchases.
Payment settlement times affect how the business plans. This is why settlement is not just a technical payment topic. It is a business operations topic. When business owners understand their settlement schedule, they can plan cash flow with more confidence.
How the Payment Settlement Process Usually Works
The full settlement process can sound complicated, but the basic flow is easier to understand when explained in plain language. First, the customer pays with a credit card or debit card. The payment is authorized through the payment network and card issuer. The business receives approval, and the sale is completed.
Next, the transaction is added to a batch. A batch is a group of transactions that the business or payment system sends for settlement. Some businesses close batches manually, while others use automatic batching.
After the batch is submitted, the transactions move through settlement. The payment networks, issuing banks, acquiring bank, and processor handle the movement of funds and transaction details. Finally, the processor or merchant services provider funds the business according to the payout or funding schedule.
The business sees the deposit in its bank account after that process is complete. This is why a card payment deposit may not perfectly match the exact time of sale. It may be grouped with other transactions, affected by the close-of-day time, and deposited based on the processor’s funding rules.
What Is Batch Settlement?
Batch settlement is the process of submitting a group of card transactions for settlement. Think of it like closing out the day’s card payments.
A business may accept payments all day. Instead of each transaction settling separately the moment it happens, the payment system may group those transactions into a batch. When the batch closes, those payments move forward for settlement and funding.
Batch timing matters because it can affect when the funds are sent to the business. For example, a business may process sales before the cutoff time and receive funds according to the next available funding schedule. But if transactions are batched after the cutoff, they may move into the next settlement window.
For a small business, this means one missed batch or late closeout can create a deposit delay. This is especially important for restaurants, bars, retail stores, salons, and other businesses that process payments late in the day or after normal banking hours.
What Is a Batch Cutoff Time?
A batch cutoff time is the time by which transactions need to be submitted to qualify for a certain funding schedule. This is one of the most important settlement concepts for business owners.
A payment taken before the cutoff may be included in that day’s batch. A payment taken after the cutoff may move to the next batch. That difference can affect when the money reaches the bank.
Some businesses do not realize their cutoff time until they see a deposit arrive later than expected. A retail store may process transactions after the cutoff and wonder why the deposit did not arrive with the previous day’s sales. A restaurant may close late at night and need a settlement schedule that matches its actual operating hours. A service business may take payments in the evening and see those funds arrive later because they missed the batch window.
The lesson is simple: business owners should know their batch cutoff time. When you understand the cutoff, you can better understand why some payments arrive quickly and others take longer.
What Is Merchant Funding?
Merchant funding is the part of the process where card payment funds are deposited into the business bank account. This is the moment most owners care about most.
The sale happened. The batch closed. The settlement process moved forward. Now the money is deposited. But funding timing can vary. Some businesses may have next-day funding. Others may have two-day funding, three-day funding, or another schedule based on the provider, business type, risk profile, payment method, and merchant account setup.
For small businesses, merchant funding should be clear and predictable. A business owner should know when funds are expected, how deposits are reported, and what may cause delays.
Why Friday, Weekend, and Holiday Payments Can Feel Confusing
Weekend and holiday payments often confuse business owners. A business may have a strong Friday, Saturday, and Sunday. The owner checks the bank account and expects to see all sales quickly. But the deposit may not arrive exactly when expected because funding schedules often depend on business days, bank processing, processor rules, and cutoff times.
This can be especially frustrating for restaurants, cafés, retail stores, event vendors, salons, and entertainment businesses that do a large share of sales on weekends.
The issue is not always a problem with the transaction. It may simply be the difference between the sales day, batch day, settlement day, and funding day.
That is why businesses should understand how their processor handles weekends and holidays. Owners should know whether the provider funds on weekends, whether Saturday and Sunday sales are combined, whether Friday night activity misses the batch cutoff, whether holiday deposits are delayed, and whether the bank posts deposits the same day the processor sends them.
These questions matter because they help owners plan around real cash flow instead of assumptions.
Why Deposits May Not Match Daily Sales
A common frustration is when the bank deposit does not match the sales report. This does not always mean something is wrong.
Deposits may not match daily sales because transactions may be grouped by batch, processed after cutoff, adjusted for fees, affected by refunds, reduced by chargebacks, split across multiple deposits, or delayed due to risk review.
A business may see $4,000 in card sales for the day but receive a different deposit amount because some payments were batched differently, some were refunded, or fees were deducted before deposit depending on the merchant setup.
For a business owner, this is why reporting matters. Strong reporting helps connect sales, batches, deposits, fees, refunds, and adjustments. Without that visibility, the owner may waste time trying to understand where the money went.
Apex One Payments supports businesses with merchant services for small business that can help owners think through payment workflows, reporting, and processing needs more clearly.
Next-Day Funding: What It Really Means
Next-day funding sounds simple, but business owners should understand what it means in their specific setup. In many cases, next-day funding means funds from eligible transactions are sent to the business bank account on the next business day after settlement or batch close, depending on the provider’s rules.
But not every transaction may qualify. Timing may depend on the batch cutoff, business type, bank account, risk profile, payment method, and processor agreement.
For Apex content, the key message should be honest and practical. Next-day funding can be useful, but business owners should ask exactly how it works, what payments qualify, what cutoff applies, and whether fees or account conditions affect it.
Fast funding is valuable, but clarity is just as important. A business should not only ask, “How fast do I get paid?” It should also ask, “What exactly controls that timing?”
Same-Day and Instant Funding: What to Know
Some payment providers offer faster funding options, such as same-day or instant payouts. These can be helpful when a business needs faster access to money. But they may come with extra fees, limits, eligibility requirements, or account restrictions.
For small businesses, faster funding can be useful, but it should not be judged only by speed. The business should ask whether there are extra costs, transaction limits, daily limits, eligibility rules, bank requirements, or settlement conditions.
Fast funding can help cash flow, but a reliable and transparent funding schedule is just as important. A business owner should not choose a payment provider only because the word “instant” appears in the marketing. The full business payment processing relationship still matters.
Why the First Deposit Can Take Longer
New merchants sometimes worry when their first deposit takes longer than expected. This can happen because new accounts may go through onboarding, verification, risk checks, bank account validation, or initial payout timing rules.
The exact timing depends on the provider and business setup, but the general lesson is useful for all business owners: ask about the first funding timeline before you start processing.
A new business should not assume the first card payment will appear immediately. It should understand when the first deposit is expected and what verification steps may be required.
This is especially important for new restaurants, retail stores, healthcare offices, service businesses, and startups that depend on early cash flow.
ACH Payments and Card Payments May Settle Differently
Card payments and ACH payments do not always settle on the same timeline. Card payments move through card networks. ACH payments move through banking systems. Because of that, ACH can have different processing and settlement timing than credit card or debit card payments.
For businesses that accept both card and ACH payments, this matters. A professional services firm may collect invoices by ACH. A healthcare office may use payment plans. A contractor may accept large bank payments. A service business may use ACH for recurring billing.
The business owner should not expect every payment method to deposit on the same timeline. The payment method affects the funding experience. This is why business payment processing should be reviewed as a full workflow, not just a card rate.
How Payment Settlement Affects Restaurants
Restaurants often have some of the most confusing settlement patterns because they operate long hours, process tips, close late, and do strong weekend sales.
A restaurant may process payments at lunch, dinner, late night, and sometimes after midnight. Tips may need to be adjusted before batching. If the close-of-day time does not match the restaurant’s actual operating hours, reports and deposits may feel confusing.
A restaurant owner should understand when the batch closes, how tips are included, how weekend funding works, and how deposits appear in the bank. A payment setup that works for a 9-to-5 retail store may not be the best fit for a restaurant that closes late.
Apex One Payments supports restaurant POS systems and payment workflows, making settlement clarity especially important for restaurant operators who need daily sales, tips, deposits, and reporting to make sense.
How Payment Settlement Affects Retail Stores
Retail stores depend on predictable deposits to manage inventory, payroll, and supplier payments. A store owner may need to order new stock quickly after a busy weekend or seasonal promotion. If card payment deposits are delayed or hard to match, it can create unnecessary planning problems.
Retailers also need deposit reporting that connects sales, refunds, chargebacks, adjustments, and batch totals. Without clear reporting, it becomes harder to understand actual cash flow.
A good retail payment setup should help the owner know what was sold, what was refunded, what was deposited, and what fees or adjustments were involved.
Apex One Payments provides retail payment processing support for stores that need stronger checkout, payment acceptance, and business payment visibility.
How Payment Settlement Affects Healthcare Offices
Healthcare payment workflows can be different from restaurants or retail. A healthcare office may collect copays, patient balances, payment plans, deposits, and follow-up payments. Some payments happen at the front desk. Others may happen over the phone or through online payment tools.
When settlement reporting is unclear, staff may struggle to match patient payments with deposits. This can create confusion between billing, front-desk records, accounting, and bank activity.
Healthcare offices need a payment process that is secure, organized, and easy to reconcile. Apex One Payments’ healthcare payment processing solutions connect naturally with this topic because medical offices need payment workflows that support both patient convenience and administrative clarity.
How Settlement Affects Service Businesses and Contractors
Service businesses and contractors often deal with deposits, final balances, remote payments, and job-based collections. A contractor may collect a deposit before ordering materials. A repair business may take payment when the job is approved. A consultant may invoice after a project milestone. A mobile service business may collect payment in the field.
In these situations, settlement timing matters because the business may need funds quickly to continue the job, pay staff, buy supplies, or schedule the next service.
A service business should understand how card payments, keyed payments, payment links, virtual terminal payments, and invoices settle. This is especially important for card-not-present payments, which may have different risk and funding considerations depending on the provider.
Apex One Payments’ business payment solutions can support service businesses that want cleaner payment workflows and better visibility into deposits.
What Causes Payment Deposit Delays?
Payment deposit delays can happen for several reasons. A batch may be submitted after the cutoff. A bank holiday may delay posting. A weekend may affect the timeline. A transaction may be under review. The merchant account may need additional verification. A chargeback, refund, or adjustment may affect the deposit. The connected bank account may have an issue. The business may be using a payment method with a longer settlement timeline.
The important thing is not to panic immediately. A delayed deposit does not always mean the payment failed. But the business should have clear reporting and a provider that can explain what is happening.
If an owner cannot understand why deposits are late, it may be time to review the payment processor relationship.
Why Reporting Is Just as Important as Funding Speed
Many business owners focus only on speed. They ask, “How fast will I get paid?” That question matters, but it is not the only question.
A better question is: “Will I clearly understand my deposits?”
Fast funding is helpful, but if reports are confusing, deposits do not match sales, fees are hard to track, and support cannot explain the difference, the business still has a problem.
Good reporting should help the owner see sales, batches, deposits, refunds, chargebacks, adjustments, and fees in a way that makes sense. This is especially important for businesses with multiple payment methods, multiple locations, staff users, online payments, invoices, and recurring billing.
Payment processing deposits should not feel like a mystery. A provider should help make the flow of money easier to understand.
Settlement Timing and Merchant Statements
Merchant statements can reveal a lot about funding and deposits. They may show batch totals, daily deposits, processing fees, adjustments, chargebacks, refunds, and other activity. But many business owners do not read them closely because the statements feel complicated.
That is a missed opportunity. A merchant statement can help the business understand how payments are being processed and where costs or delays may appear.
Apex already has strong content around merchant statement review, and this settlement blog can support that topic naturally. Business owners who are unsure what they are paying can also use the Apex One Payments payment savings calculator to start reviewing payment processing costs more clearly.
Settlement timing, fees, and reporting all connect. When business owners understand the statement, they understand the payment relationship better.
What to Ask Your Payment Processor About Settlement
A small business owner does not need to know every technical detail of card networks, but they should ask smart questions before choosing or staying with a payment provider.
Ask when card payments are typically funded, what the batch cutoff time is, whether the business qualifies for next-day funding, how weekend and holiday payments are handled, whether tips, refunds, chargebacks, and adjustments affect deposit timing, how deposits appear on merchant statements, whether fees are deducted daily or monthly, how to match batch totals with bank deposits, what happens if a batch is missed, and who to contact if a deposit is delayed.
These are practical business questions. A good payment provider should answer them clearly. If the provider cannot explain settlement in simple language, that is a warning sign.
Why the Cheapest Processor May Not Be the Best Funding Partner
Many business owners choose payment processing by looking only at rates. Lower fees are important, but settlement clarity matters too.
A cheap processor that creates confusion around deposits, reporting, support, batch timing, or funding delays may cost the business more time and stress than expected.
The best payment processor is not always the one with the lowest advertised rate. It is the one that gives the business the right mix of pricing, support, funding clarity, hardware, reporting, and payment options.
A business owner should look at the complete setup. How fast are funds deposited? How clear are reports? How helpful is support? How easy is it to understand fees? Does the provider explain batch settlement? Does the system fit the way the business operates?
This is where merchant services for small business should be viewed as a full business relationship, not just a transaction rate.
How POS Systems and Payment Hardware Affect Settlement Clarity
Your POS system and payment hardware can affect how easy it is to understand payments. A good POS setup should help connect transactions, receipts, batches, refunds, tips, and reports. A poor setup may make the owner jump between systems just to understand what happened.
For example, a restaurant POS should help the owner track sales, tips, close-of-day activity, and deposits. A retail POS should help connect transactions with items, returns, and batch totals. A healthcare office should be able to connect patient payments with reporting. A service business should be able to track invoices and payment activity clearly.
The payment device itself matters too. Updated, reliable hardware can reduce checkout issues and help transactions process smoothly. Businesses that need physical payment devices can review Apex One Payments’ POS terminals and payment hardware or explore the Free Dejavoo QD2 card payment terminal offer for qualified businesses.
The goal is not just accepting payments. The goal is accepting payments in a way that is easy to track.
How Apex One Payments Can Help Businesses Understand Payment Settlement
Apex One Payments helps businesses choose payment processing, POS terminal solutions, credit card processing, and merchant services that fit real business operations.
For settlement timing, the value is clarity. Business owners should understand how payments are accepted, when batches close, when deposits are expected, how fees are handled, and what to do when funding looks delayed.
Apex One Payments can help business owners review their current setup, compare payment processing options, look at POS hardware needs, and ask the right questions about funding, deposits, and merchant services.
A payment processor should not make money movement harder to understand. It should make payment processing feel simpler.
Final Thoughts: Payment Settlement Is Really About Cash Flow Confidence
Payment settlement times matter because cash flow matters. Accepting a payment is only part of the process. Business owners also need to know when that money will reach the bank, how deposits are grouped, why timing may change, and how to match sales reports with bank activity.
When settlement is unclear, owners waste time checking dashboards, calling support, comparing bank deposits, and wondering whether something is wrong. When settlement is clear, the business can plan better.
A restaurant can understand weekend funding. A retail store can plan inventory. A healthcare office can match patient payments. A contractor can schedule materials. A service business can track invoice payments. A professional firm can manage cash flow with more confidence.
The right business payment processing setup should help owners accept payments, track deposits, understand fees, and reduce confusion.
Apex One Payments can help small businesses explore better payment processing solutions, review POS terminals and payment hardware, understand merchant services options, and build a payment workflow that supports smoother cash flow.
For business owners who want clearer deposits, better reporting, and a payment provider that explains the process in plain language, the next step is simple: contact Apex One Payments and review your current payment setup.
FAQs
What are payment settlement times?
Payment settlement times refer to how long it takes for card payment funds to move through the payment system and reach the business bank account.
Is payment authorization the same as settlement?
No. Authorization means the card payment was approved. Settlement and funding happen later, when the transaction is processed and money is sent to the merchant’s bank account.
Why do card payments take time to reach my bank?
Card payments may take time because transactions need to be batched, settled, processed, and funded according to the provider’s payout schedule, bank timing, and cutoff rules.
What is batch settlement?
Batch settlement is the process of grouping card transactions and submitting them for settlement. The batch close time can affect when funds reach the business bank account.
What is next-day funding?
Next-day funding usually means eligible transactions are funded to the business bank account on the next business day, depending on the provider, batch cutoff, bank, and account setup.
Why are my card payment deposits delayed?
Deposits may be delayed because of missed batch cutoffs, weekends, holidays, bank processing, refunds, chargebacks, account reviews, verification issues, or payment method timing.
Why does my deposit not match my daily sales?
Deposits may not match daily sales because of batch timing, deducted fees, refunds, chargebacks, adjustments, split deposits, or transactions processed after the cutoff.
How can Apex One Payments help with payment settlement?
Apex One Payments helps businesses review payment processing, merchant services, POS terminals, payment hardware, reporting, and funding questions so owners can better understand when card payments reach their bank.